Key Report Findings
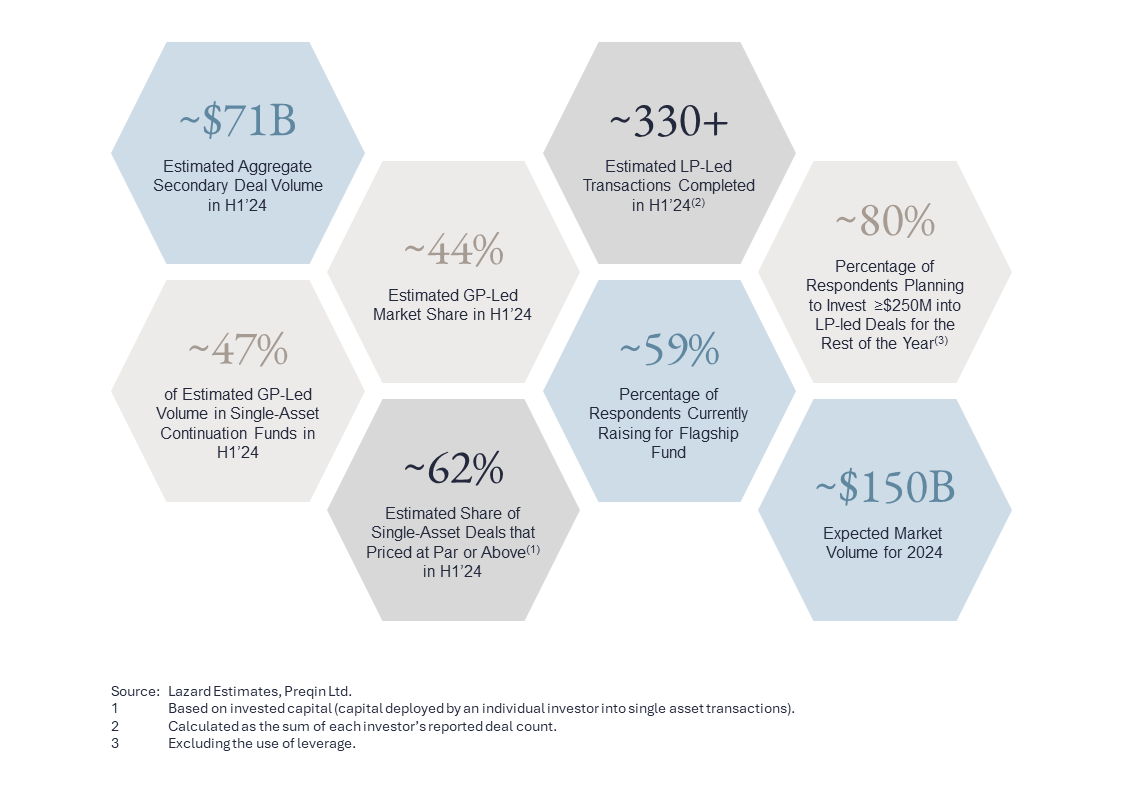
The secondary market had a strong start in H1’24 and is anticipated to surpass its 2023 performance, with continued growth expected in the forthcoming years
A surge in GP-led and LP-led deals is forecasted to persist in H2’24, propelled by the emergence of new capital sources, including specialist investors and increasing ’40 Act funds AUM
Despite an anticipated increase in M&A and IPO activities, secondary deal volume is expected to remain robust going forward given GP’s and LP’s increasing predisposition to actively manage their portfolios
Six Predictions for the H2 2024
Record-breaking market volume in FY 2024 given strong H1’24 performance
Accelerating GP-led transaction volume in H2’24 driven by demand for continuation funds, particularly for Single-Asset transactions
Bid-ask spreads will continue to narrow as buyside appetite grows and new entrants ramp up deployment pace, assuming recession risk recedes
Increased breadth of LP-led transactions involving traditional funds, secondary funds, co-investment portfolios and management fund opportunities
More traditional sponsors to expand their strategies to include GP-led teams, with a focus on Single-Asset continuation funds
’40 Act funds will put significant upward pressure on certain fund portfolios given increasing monthly inflows and the need to rapidly deploy that capital
Source: Lazard Estimates.